


Access advice to guide your steps
Every few months a client sends me a screenshot of a savings account advertising “5.5% interest!” and asks why they're not earning that. Almost every time, the answer is the same: they're looking at the maximum rate, not the rate they'll actually get.
High-interest savings accounts in Australia are almost never one number. They're two numbers stitched together; a base rate that applies to everyone, and a bonus rate that only applies if you jump through a specific set of hoops every single month. Miss one hoop, and you fall straight back to the base rate for that month. Sometimes the next month too.
The problem is the base rate is often so low it's basically a rounding error. So the account that looks the most generous on a comparison table can quietly be the least generous account you own, in any month where life gets in the way.
ING's Savings Maximiser currently advertises up to 5.50% p.a. on balances up to $100,000. Sounds great; until you look at how it's built:
- Base rate: 0.01% p.a. (yes, one hundredth of one percent)
- Bonus rate: 5.49% p.a., on top of the base, only if you meet all three of these in a calendar month:
And here's the sting most people miss: even if you nail all three conditions, the bonus rate doesn't apply that month; it applies the following calendar month. So there's always a one-month lag between doing the right thing and getting paid for it.
Fail any one of the three in a given month, and that account earns 0.01% for the following month. On $100,000, that's about 83 cents in interest for the month, instead of roughly $458.
Macquarie's Personal Savings Account currently pays 5.00% p.a., flat, on balances up to $2 million. No deposit minimum, no card-spend quota, no “grow your balance” test. You get 5% whether you're actively managing the account or you forgot it exists for three months.
It's not the headline rate. But it's the rate you actually get, every month, without having to think about it.
Using a $100,000 balance (ING's cap) and comparing a full year:
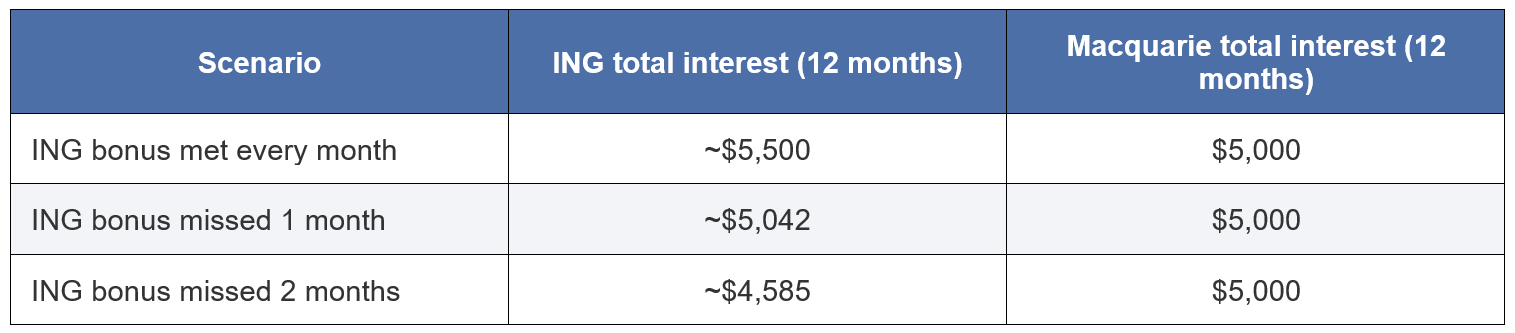
Meet the ING conditions perfectly, all year, and you finish around $500 ahead of Macquarie on $100k, that's the number on the comparison website.
Put another way: an account requiring 36 separate conditions to be met correctly across a year (three conditions, twelve months) only needs to fail twice before the “no hoops” account wins outright. And that's before accounting for the one-month lag working against you, or for balances sitting above $100,000, which earn ING's 0.01% regardless of what you do.
Both are legitimate accounts and this isn't advice to move your money, it's a maths lesson in what “up to X%” actually means. If you're disciplined, watch your card spend, and won't need to touch the balance mid-month, the ING structure can genuinely pay more. If your income or spending is even slightly irregular, which describes most people, most years, a lower rate with zero conditions can easily out-earn the “higher” rate advertised everywhere.
The rate that matters isn't the one in the ad. It's the one you'll actually earn in your worst month, twelve times a year.

This website may contain general advice, but does not take into account your objectives, financial situation or needs. You should consider whether the advice is suitable for you and your personal circumstances. Before you make any decision about whether to acquire a certain product, you should obtain and read the relevant product disclosure statement. In the event that Funded Futures Financial Services is providing personal advice it will be communicated via a ‘statement of advice’.
Funded Futures Financial Planning ABN 81 646 656 804 T/A Funded Futures Financial Services is a Corporate Authorised Representatives and is authorised through Cobalt Advisers Pty Ltd ABN 64 628 654 099 who is an Australian Financial Services Licencee # 512550.
© 2024 Funded Futures | All Rights Reserved | Developed by
