


Access advice to guide your steps
More of the clients I speak to are talking about getting out of the suburbs: a few acres, some space, a bit of a hobby farm. It's a great lifestyle move. But for anyone who expects to rely on the Age Pension one day, there's a number in the rules that can quietly change the answer: two hectares.
The family home is exempt from the Age Pension assets test. But the exemption doesn't cover unlimited land. Buy a property that's too big, and part of what you thought was your home becomes an assessable asset.
For the Age Pension assets test, Services Australia treats your principal home as the home you live in plus the first 2 hectares of land it sits on, provided the land is on a single title. Land beyond the first 2 hectares is normally counted in the assets test. A home on 6 hectares, for example, has 4 hectares counted.
A few related rules sit alongside it:
• A second title is assessable. Adjoining land on a separate title is generally an assessable asset, even if it looks like part of the same property.
• Business use counts. If part of the home or land is used only for business, that part is assessable.
• Other buildings and equipment. Commercial buildings, farm buildings, and plant and equipment are assessable.
• Separate dwellings. A cottage on the same title rented to someone else is an assessable asset, though the principal home and its surrounding land stay exempt.
The exemption also only applies to a home you actually live in. It's the principal home test, not a general land test.
The exemption also only applies to a home you actually live in. It's the principal home test, not a general land test.
There is a concession for larger properties, called the extended land use test. If the home and land are on a single title over 2 hectares, the whole property can stay exempt if all of the following apply:
• You're of Age Pension age and receive or qualify for the Age Pension, Carer Payment or a DVA service pension.
• You have a continuous 20-year attachment to the land as your principal home. Temporary absences of under 12 months don't break it.
• You make effective use of productive land to generate income, taking your capacity into account.
The 20-year requirement is the catch. It is designed for farming families who have lived on and worked the same property for most of their lives. Someone who buys a block at 60 to get away from the suburbs can't meet it, however well they use the land. Services Australia's own guidance gives an example of a property owned for 17 years that doesn't qualify.
Where the extended test isn't met, the test falls back to private land use. Only the first 2 hectares of land used for private or domestic purposes is exempt, and the rest is assessed. The value of the excess land is worked out from the difference between the value of the home with its 2 hectares and the value of the whole title. Services Australia revalues properties like this every two years.
There are narrow exceptions that let land on more than one title be treated as a single title, such as a home built across two blocks, heritage-protected land that can't be sold separately, or a block holding the house's septic system or bore water. They are limited, and alterations to the house or its infrastructure since 8 May 2006 can bar the last one.
What it looks like in dollars
From 20 September 2026, a single homeowner can hold $333,000 of assessable assets before their Age Pension starts to reduce under the assets test, and the pension cuts out at $745,750. Above $333,000, the pension reduces by $3 a fortnight for every $1,000 of assets.
Take a single homeowner with $400,000 of other assessable assets, such as super and savings, who buys a property with a house on 8 hectares. Say the house and its first 2 hectares are worth $700,000, and the other 6 hectares are worth $200,000.
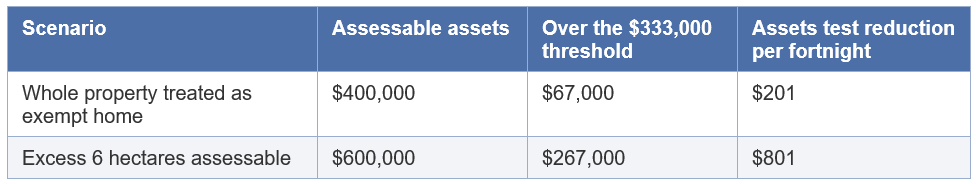
The extra land costs $600 a fortnight, or $15,600 a year, in Age Pension. That's for a block most people would think of as part of the house.
This is a simplified example. It ignores the income test, which could produce a lower pension again, any income earned from the land, and the value of farm buildings and equipment, which are assessable on top. The land would also be valued at current market value through Services Australia's own process, which may differ from what you paid.
None of this means a hobby farm is a bad idea. It means the land size and the title structure are worth checking before you sign, rather than after the Age Pension claim is lodged:
• How big is the title? Count hectares on the title, not on the listing. Anything over 2 hectares on the home's title is likely to be assessed.
• Is it one title or several? Adjoining land on a separate title is generally assessable, and combining titles to cut what's assessable can be treated as deprivation.
• How will the land be used? Land used for business or income changes how it's assessed, and any income it produces counts under the income test.
• Are there other structures? A rented cottage, commercial buildings, farm sheds and equipment can all be assessable.
• When will you want to claim? The extended land use test needs 20 years of attachment. A move late in life won't get there.
If you're a long way from Age Pension age, the thresholds, the rules and the land itself can all change before you claim. That's another reason to run the numbers early.
If you're considering a move to acreage, or you already own a larger block, it's worth looking at how it would be treated for the Age Pension before you commit. Get in touch with the team at Funded Futures and we'll walk through your situation with you.
• Services Australia, Real estate assets
• Services Australia operational guide, Assessing house and curtilage
• Services Australia operational guide, principal home and land over 2 hectares
• Social Security Guide, assets test reduction rate (4.2.3)
• Rest Super, Age Pension rates and limits from 20 September 2026
• The Motley Fool Australia, Age Pension asset limits from 20 September 2026

This website may contain general advice, but does not take into account your objectives, financial situation or needs. You should consider whether the advice is suitable for you and your personal circumstances. Before you make any decision about whether to acquire a certain product, you should obtain and read the relevant product disclosure statement. In the event that Funded Futures Financial Services is providing personal advice it will be communicated via a ‘statement of advice’.
Funded Futures Financial Planning ABN 81 646 656 804 T/A Funded Futures Financial Services is a Corporate Authorised Representatives and is authorised through Cobalt Advisers Pty Ltd ABN 64 628 654 099 who is an Australian Financial Services Licencee # 512550.
© 2024 Funded Futures | All Rights Reserved | Developed by
