


Access advice to guide your steps
For about twenty years, the idea behind a balanced portfolio was simple. When shares fell, bonds tended to rise, so holding both smoothed the ride. That's why bonds earned the label "defensive".
Then 2022 happened. Shares and bonds fell together, and a lot of people who thought they had a cushion found out they didn't. Last month it looked like déjà vu: Australian shares fell, and the 10-year government bond yield, which moves in the opposite direction to bond prices, climbed to around 5.4%, its highest in about 15 years.
So is the old partnership over, and is it coming back? The honest answer is that it depends on what the market is worried about.
Here's the part that surprises most people. Over the long run, shares and bonds have often moved together. US research covering 1970 to 1999 found a positive relationship between the two. From 2000 to 2022 it flipped to negative, which is the period most of us remember and the one many portfolios were built around.
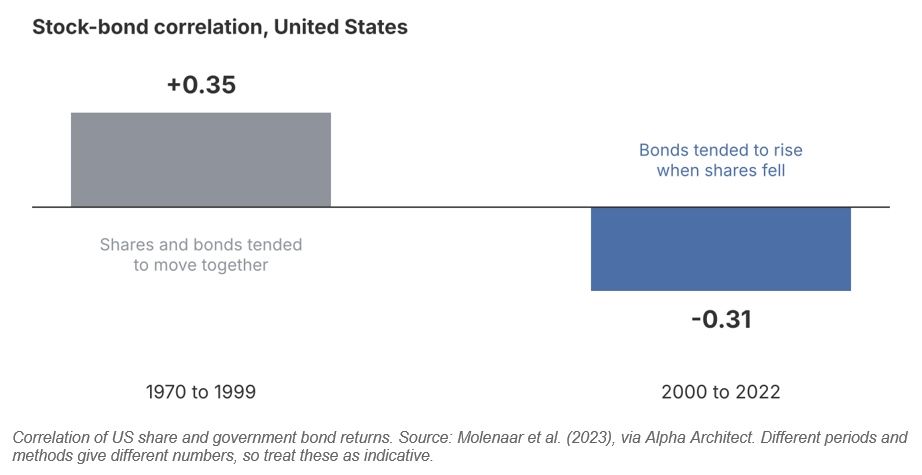
A correlation of +1 means two things move in lockstep, and -1 means they move in opposite directions. The two eras sit on either side of zero. The researchers' explanation is inflation. When inflation is low and steady, the main thing that scares markets is a weak economy. In that case, investors buy bonds and central banks cut rates, so bonds rise while shares fall. When inflation is high or unpredictable, the main worry becomes rising interest rates, and those hurt both.
In other words, the twenty-year stretch that built our expectations was a product of a particular economic backdrop, not a law of nature.
Inflation came back and central banks raised rates quickly. In the US, shares fell about 18% in 2022 and long-term government bonds fell about 26%. A traditional 60/40 portfolio lost around 20%. The IMF says the shift in the relationship dates to around the end of 2019, and that supply shocks and persistent inflation have weakened the hedge since.
The years of near-zero interest rates made it worse. When rates are already at zero, bonds have little room to rise further in a crisis, and they have a long way to fall when rates go back up. Higher starting yields change that arithmetic.
Partly, and it's conditional. Here's what has changed, and what hasn't:
• Interest rates are no longer at zero. The cash rate is 4.60% and long-term yields are well above where they were. That means bonds pay you more to hold them, and if the economy weakens, there is room to cut rates, which is the mechanism that makes bonds rise when shares fall.
• Central banks have stopped buying. The emergency bond buying of the COVID years has ended and central banks are letting their holdings run off. That removes a big buyer, and at the same time governments are issuing more debt. The IMF points to this as one reason investors now demand more to hold long-term bonds.
• Inflation is still the swing factor. The correlation has been unstable. One analysis of US data found it was negative in 2025 and bonds helped cushion a share market fall in March this year, but it turned positive again in 2026 as inflation worries returned. Forecasters disagree. One major research house expected it to turn positive again this year, because it doesn't see low, steady inflation coming back on a lasting basis.
So the realistic answer is that bonds help when the problem is a weak economy, and they struggle when the problem is inflation. You can't know in advance which one the next shock will be.
None of this means bonds are useless. It means they're not a guarantee, and the word "defensive" needs more precision than it usually gets.
• Ask what the defensive part of your portfolio is for. Is it income, is it a buffer you can draw on while shares recover, or is it a hedge against a share market fall? Different holdings do different jobs.
• Duration matters. Longer-dated bonds are more sensitive to interest rate changes, in both directions. Shorter-dated holdings and cash behave quite differently from long-dated bonds when rates move.
• Don't rely on a single protection. A plan that only works if bonds rise when shares fall is a plan with one point of failure. A cash buffer for the next few years of spending, a spread of different assets, and a sensible mix for your time horizon give you more than one line of defence.
• Review what you assumed. If your portfolio was designed on the 2000 to 2020 pattern, it's worth checking that the assumptions still hold.
Past correlations aren't a forecast. The goal isn't to predict which regime we're in. It's to build a plan that still works if the answer turns out to be the uncomfortable one. Information is based on US data (as there is more of it compared to Australian data), however the premises should hold true.

This website may contain general advice, but does not take into account your objectives, financial situation or needs. You should consider whether the advice is suitable for you and your personal circumstances. Before you make any decision about whether to acquire a certain product, you should obtain and read the relevant product disclosure statement. In the event that Funded Futures Financial Services is providing personal advice it will be communicated via a ‘statement of advice’.
Funded Futures Financial Planning ABN 81 646 656 804 T/A Funded Futures Financial Services is a Corporate Authorised Representatives and is authorised through Cobalt Advisers Pty Ltd ABN 64 628 654 099 who is an Australian Financial Services Licencee # 512550.
© 2024 Funded Futures | All Rights Reserved | Developed by
