


Access advice to guide your steps
I was standing around at baseball practice yesterday waiting for fly ball drills, and, true to form, my brain doesn't switch off. Someone mentioned how much their club registration was costing them this season, and a tradie standing nearby said “just get your employer to sponsor you.” My brain went straight to “that's an FBT issue”; sponsorship packages like this, where a business pays a specific player's registration fee, sometimes upward of $500, aren't the tax-free gesture they sound like. I started explaining there's no real nexus between playing a season of club sport and the income-producing activities of your actual job, and got the classic pushback: “nah, it keeps me fit, and I need to be fit for my job.” Luckily it was my turn to catch, so I got to make a swift escape rather than quoting the FBTAA 1986. And I needed some content, so here we are.
It's a good example of something that comes up constantly in small business, an arrangement that feels like a harmless, generous gesture, described using a word (“sponsorship”) that makes it sound like a straightforward business expense, when the tax treatment underneath is actually a lot narrower than most people assume.
Fringe Benefits Tax exists to stop salary and wages being dressed up as something else. The test the ATO applies is simple to say and often uncomfortable in practice: would you have provided this benefit if the person weren't your employee? A business doesn't pay a stranger's kid's netball fees. It pays its employee's fees, specifically because they're an employee. That's enough to bring it into fringe benefit territory, regardless of what the sports club calls the arrangement on their sponsorship page.
Once something is a fringe benefit, there are really only two doors out of paying FBT on it: the minor benefits exemption, or the “otherwise deductible” rule. Neither opens easily here.
The minor benefits exemption needs the benefit to be under $300 and infrequent or irregular. At $500 a season, it fails on value alone, how often it happens doesn't matter once you're over the threshold.
The otherwise deductible rule is the one that catches people out, and it's exactly where the tradie and I landed. This rule only reduces the taxable value if the employee could have claimed the expense as their own tax deduction, had they paid for it themselves. And this is where “it keeps me fit and I need to be fit for my job” runs into a wall; because that's not actually the test. The ATO's own guidance is explicit on this: members of the regular Defence Force, police officers and firefighters generally can't claim their own fitness expenses either, even though fitness is unambiguously part of the job. The only exception is where strenuous physical activity is itself an essential, regular, and direct part of performing your actual duties, the ATO's own example is a police academy physical training instructor, whose job is to physically demonstrate and lead the training. A general duties officer, a firefighter, or a tradie who simply needs to be fit to be capable of doing physical work doesn't meet that bar. Needing to be fit for your job and the act of getting fit being your job are two different things, and the ATO draws that line firmly.
So a genuine, no-catch bit of good news it is not; but it's a very common, very understandable misunderstanding, and a useful one to get right before money changes hands.
If your employer offers to cover a season's registration fee, it's worth understanding what you're actually accepting, not because it's a bad deal, but because “free” isn't quite the right word for it.
It's tracked, even if it doesn't show up as income. Fringe benefits your employer provides across an FBT year (1 April to 31 March) get grossed up for reporting purposes, and if the total grossed-up value from that employer exceeds $2,000 in the year, it appears on your income statement as a Reportable Fringe Benefits Amount (RFBA). A single $500 sponsorship might not get you there on its own, but it stacks with anything else, a novated lease, a phone plan, another benefit, so it's worth knowing it's being counted somewhere, even though it isn't added to your taxable income directly.
RFBA still affects a surprising number of things it isn't supposed to touch. Even though it doesn't change your income tax bill, it's included in the income tests for:
None of that makes the sponsorship a bad thing to accept. It just means someone on a HELP debt or receiving family payments should have that in mind before assuming it's a completely free $500, it's more like $500 that shows up in a couple of places you wouldn't expect.
If a staff member asks you to sponsor their season, or a club's sponsorship pack lands on your desk with an individual player's name attached, a few things are worth working through before you say yes.
Work out what you're actually paying for. If the arrangement pays a named employee's individual registration fee, that's a fringe benefit, full stop; the “sponsorship” label doesn't change the substance. If instead you're paying for genuine advertising exposure, a fence banner, a logo on the guernsey/jersey, a mention in the club newsletter, with no individual employee nominated as the beneficiary, that's a normal deductible marketing expense with no FBT at all. The distinguishing question is simple: is this benefit that person's, or is it the club's, in exchange for putting your name on something?
Understand what it actually costs once it's a fringe benefit. FBT is 47% of the grossed-up value, not the raw dollar figure; and this is the number that tends to change minds. Assuming no GST credit is available (likely, since many community clubs aren't charging GST on registration fees), the Type 2 gross-up rate of roughly 1.8868 applies:
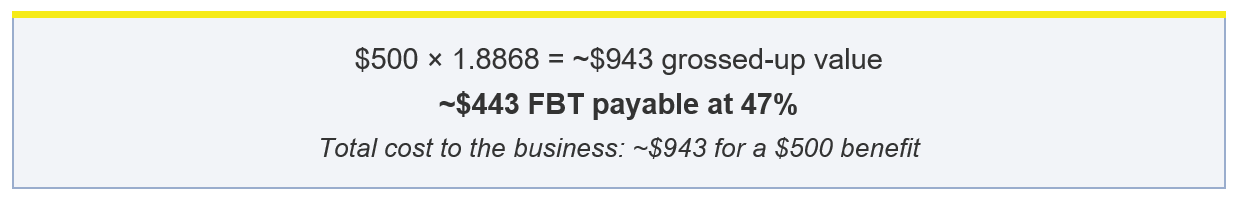
So a “$500 sponsorship” costs the business closer to $940 all-in once FBT is added on top — nearly double the number that got agreed to verbally at training or over a beer. That's worth knowing before it's offered to a whole team, not after the FBT return is due.
Check the exemptions honestly, rather than hopefully. The minor benefits exemption won't apply at this value. The otherwise deductible rule won't reduce it either, for the same reason it didn't work for the tradie, a season of club sport isn't income-producing activity for almost any employee, regardless of how physical their day job is. And the exemption for employer-provided recreational facilities only covers facilities on your own business premises, an external club or gym doesn't qualify, no matter how you structure the payment.
Know your alternatives. If the goal is genuinely to support the club rather than reward one specific employee, straight sponsorship; advertising, no individual named; sidesteps FBT entirely and is simply deductible. If the goal is to reward or support a specific employee, a cash bonus is transparent: no FBT, straightforward PAYG withholding, and the employee can see exactly what they received and decide how to spend it. Either can work, the mistake is assuming a $500 rego fee threads a needle that, in practice, doesn't exist.
Talk to your accountant or tax agent before it becomes a pattern. One employee, one season, might be a manageable one-off decision either way. A club-wide sponsorship deal covering half your workforce is a different conversation, worth having with whoever prepares your FBT return before it becomes a habit rather than a one-off.

This website may contain general advice, but does not take into account your objectives, financial situation or needs. You should consider whether the advice is suitable for you and your personal circumstances. Before you make any decision about whether to acquire a certain product, you should obtain and read the relevant product disclosure statement. In the event that Funded Futures Financial Services is providing personal advice it will be communicated via a ‘statement of advice’.
Funded Futures Financial Planning ABN 81 646 656 804 T/A Funded Futures Financial Services is a Corporate Authorised Representatives and is authorised through Cobalt Advisers Pty Ltd ABN 64 628 654 099 who is an Australian Financial Services Licencee # 512550.
© 2024 Funded Futures | All Rights Reserved | Developed by
